Loading market data...
Articles

Cryptocurrency vs. Traditional Investments: A Comparison

Yashovardhan Sharma
Written By Yashovardhan Sharma - Jun 21, 2024
Cryptocurrency vs. Traditional Investments: A Comparison

Image Source: Game of Life

A good investment portfolio should mix different types of assets. Spreading your money across stocks, bonds, real estate, and commodities helps manage risk. You can even throw in some riskier investments. Back in the day, it might have been oil drilling or internet stocks in the '90s. Now, it's all about cryptocurrency. When comparing crypto and stocks, investors need to weigh their comfort with risk. Crypto can be super volatile, with price swings that can make stocks seem stable by comparison. Knowing the pros and cons of each investment and how they fit into your portfolio is critical to reaching your goals. Let us also look at cryptocurrency vs. traditional investments in this blog. 


Quick overview of stocks

When thinking about crypto vs. stocks, remember that owning stock means you own a piece of a company. The founder initially owns it, but as the company grows, it might sell shares to investors. Eventually, the company might go public to raise more money and give early investors a chance to cash out. Even after going public, a company can issue more stock. This can dilute the value of existing shares but helps the company raise funds for things like expansion, hiring, and building new facilities. Stockholders can vote on board members and corporate policies at annual meetings. While they don't usually influence day-to-day operations, a group of investors can still steer the company's direction if they band together.


Stock owners can either have preferred or common stock. Preferred shares are called that because they offer some perks. For instance, those with preferred shares get their dividends first and usually at a higher rate. If the company goes under, they get paid out before common stockholders. Conversely, preferred shareholders don't get to vote as common stockholders do. When it comes to buying, investors can choose between common or preferred shares based on their goals.


You May Also Like Hot Wallet Vs. Cold Wallet: Guide To Crypto Security


Getting the Right Value

Investors make money when the stock's value goes up, which often happens if the company is doing well. More sales and profits usually mean a higher stock price. Even just the hope of better performance can push the price up. But, the investment loses value if the stock price drops because the company isn't doing well or due to bad economic conditions. Dividends are another way investors get value. A company might start paying dividends if they think profits can be shared, or they might cut or stop dividends if they need to reinvest in the business. Dividends, usually paid quarterly, let a company share its profits with investors. Older, more stable companies are more likely to pay dividends, while younger, fast-growing companies might reinvest profits instead of paying dividends.


Learning About Cryptocurrency

It's a pretty new way to trade stuff that's been getting a lot of buzz over the past ten years. Some folks think it's the future of money, while others worry it's too risky because it's not regulated. Cryptos don't have government support, and their value is all about what people are willing to pay. These things run on decentralized networks of computers worldwide, and they use strong encryption for security that's why they are called cryptocurrencies. To access your crypto, you need a password that's at least 16 characters long. (Some people have lost access because they forgot their passwords.)


There are tons of cryptocurrencies out there, but Bitcoin was the first and is still the most popular, making up almost two-thirds of the market in 2020. Other big names include Ethereum, Litecoin, PeerCoin, Namecoin, Cardano, and EOS. Crypto prices are all over the place, though. For instance, in 2021, Bitcoins value swung between $28,383 and over $65,000. Fans of crypto, especially Bitcoin, say it's a good hedge against inflation. Bitcoin has a cap of 21 million coins, which means there's a limited supply, unlike regular money that governments can keep printing. More and more businesses are starting to accept cryptocurrencies as payment, and platforms like Square are making it easier to do crypto transactions. In 2021, El Salvador even made Bitcoin legal tender!
 

Blockchain & Investment Vehicles


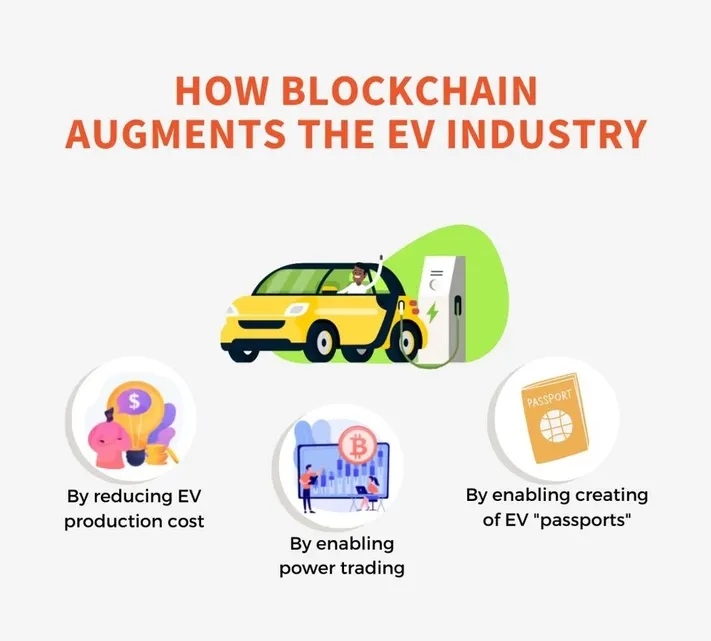
How Blockchain Augments the EV Industry

Image Source: Forbes

Cryptocurrency runs on blockchain technology, which is like a digital ledger that keeps track of all the transactions. It's a mix of cryptography, a network of computers, and user agreement to ensure everything is recorded accurately. Each transaction is stored in a block, and these blocks are linked together in a chain, making it super secure. The chain itself checks and validates all the transactions. Some folks think the absolute goldmine in cryptocurrency is the blockchain tech behind it. A bunch of companies are using blockchain to record regular currency transactions to boost trust and cut down on fraud and money laundering.


With Bitcoin prices hitting over $60,000 per coin, buying cryptocurrency can seem pricier than stocks. But you can buy smaller fractions of Bitcoin if you're not looking to spend that much. This is because of factors such as Bitcoin Halving. Unregulated entities also run crypto funds.


 Cryptocurrency hit a significant milestone as an investment in 2021 when the SEC allowed an exchange-traded fund (ETF) related to Bitcoin to start trading. This ETF tracks Bitcoin futures prices on the Chicago Mercantile Exchange, not Bitcoin's direct value. This move lets brokerage firms dive into the crypto scene with the green light from U.S. regulators.


Cryptocurrency vs. Stocks: What Separates Them

Cryptocurrency and stocks are both solid investment options, but they play different roles in your portfolio. Significant differences exist in how you buy and sell them and how they fit into your investment strategy. Let's break down the main points:


Crypto is Riskier With Higher Returns

Crypto and stocks share some similarities but also have significant differences. Savvy investors can use both in the same portfolio for different reasons. Stocks are known for stability and have been a reliable way to build wealth for a long time. On the flip side, crypto is riskier but offers the potential for big rewards. Using both can help balance out the risks and rewards in your investments.


Crypto is Mostly Unregulated

After the stock market crash in 1929, the U.S. set up the Securities and Exchange Commission (SEC) to protect investors. Companies have to share all info that might affect their stock value, so investors have a lot of data to make informed decisions. Cryptocurrencies, however, are mostly unregulated. Some people like this because crypto markets aren't tied to any government, but it also means you don't have much protection if things go south.


Wild Swings in Crypto

Stocks have always been known for sudden value changes. Good news can push a stock up, while bad news can drag it down. Stock markets can have bad days, but complete losses are rare. Cryptocurrencies, on the other hand, are famous for their wild swings. Take Ethereum, for example; it started 2021 at about $730, shot up to over $4,000 by May, dropped to around $1,780 in July, and climbed back to over $4,000 by late October.


Crypto Exchanges are New

Stocks get traded on official exchanges all over the world. These exchanges give stock buyers security, stability, and transparency, and they're designed to handle a ton of trades every day. They're tightly regulated (though the rules differ by country), which helps protect both buyers and sellers. Crypto exchanges are a newer thing. There are tons of them out there, with big names like Binance and Coinbase leading the pack. Some of these exchanges team up with third parties to make it easy to swap regular money, like U.S. dollars, for crypto.


Crypto Provides Greater Anonymity

To buy and hold stock, you usually need to open an account with a brokerage like Charles Schwab, TD Waterhouse, or Fidelity. The brokerage handles the trades and keeps the stock in your name. Newer companies like Robinhood have made this process more straightforward but offer fewer features. You'll also need to share some personal info, like your Social Security number and address. Using a brokerage adds a layer of security. One big plus of crypto is its anonymity. No one needs to know who you are when you buy crypto. You keep your assets in a virtual wallet or on a storage device like a USB drive. But with anonymity comes the responsibility of keeping your crypto safe. You have to remember where it is and keep track of a long password. If hackers get into your wallet, you're out of luck.


Similar Reads You May Enjoy: Unlocking The Power Of Regenerative Finance: A Guide
 

Crypto vs. Precious Metals, Forex, and Bonds


Crypto Vs Precious Metals

Image Source: Royal Bull

When someone says cryptocurrencies are worthless because they lack intrinsic value, comparing them to precious metals is a solid counterargument. Nowadays, people mainly invest in precious metals either for jewelry or as an alternative currency, and their value is determined by market sentiment. Investing in precious metals has its risks, like portability issues, possible import taxes, and the need for high security. On the flip side, with cryptocurrencies, there's no need for physical transfers; you need hardware or digital wallets.


Forex investors buy and sell foreign currencies, and this can be riskier than crypto because your gains depend entirely on the economy of the country involved. Bonds, fixed-income securities, are in a different league than stocks and cryptocurrencies. With bonds, you loan money to a third party and get a fixed interest payment over time. They're considered less risky and offer higher current income than stocks and cryptos. However, the long-term returns aren't as high, which makes sense given the lower risk.


Conclusion

A balanced approach that combines elements of both might be the optimal strategy. By diversifying their portfolio to include both traditional assets and cryptocurrencies, investors can benefit from the best of both worlds, leveraging the stability of conventional investments while capitalizing on the growth potential of cryptocurrencies. As the financial landscape evolves, staying informed and adaptable will be critical. Regardless of the chosen path, thorough research and a clear understanding of the risks involved will remain essential to making sound investment decisions. The future of investing is dynamic and diverse, offering numerous avenues to grow wealth and achieve financial goals.
Read Next

How to Identify Undervalued Stocks for Portfolio Growth?
Articles

How to Identify Undervalued Stocks for Portfolio Growth?

Quick TakeawaysFundamental stock analysis evaluates financial statements, earnings growth, and balance sheet strength to discover mispriced assets.Price-to-earnings and price-to-book ratios help investors measure market value against actual corporate earnings.Discounted cash flow models calculate intrinsic worth by discounting expected future cash flows to present value.High debt loads and declining profit margins signal value traps rather than genuine buying opportunities.Monitoring institutional trading and sector trends helps uncover quality companies trading below their fair market value.Every investor dreams of finding hidden financial gems before the broader market catches on. Learning How to Identify Undervalued Stocks empowers you to buy high-quality companies at a significant discount. Academic market studies demonstrate that value investing strategies historically outperform broad market indexes over long investment horizons by capitalizing on short-term market overreactions. When emotional market noise depresses a company's share price below its intrinsic worth, disciplined investors step in to capture substantial upside potential.Uncovering these opportunities requires looking beyond daily price swings and analyzing core business fundamentals. By mastering financial metrics, you can separate temporary price drops from permanent business declines. In this guide, we break down essential valuation metrics, explain how to calculate intrinsic value, evaluate key financial ratios, and help you construct a profitable value investment approach.What is Fundamental Analysis for Undervalued Stocks?Fundamental analysis for undervalued stocks involves evaluating a company's financial health, industry position, and economic moat. Rather than relying on technical charts or momentum indicators, fundamental investors examine income statements, balance sheets, and cash flow reports. This rigorous assessment reveals whether a firm generates sustainable earnings relative to its current valuation.When temporary bad news or general market selloffs push share prices down, fundamental stock analysis highlights underlying strength. Recognizing this gap between price and intrinsic value provides the safety margin necessary for long-term capital growth.Key Valuation Metrics to Identify Undervalued CompaniesEvaluating key financial ratios allows investors to benchmark a company against industry peers and historical averages.Valuation MetricFormulaPrimary PurposeIdeal IndicatorPrice to EarningsShare Price / Earnings Per ShareMeasures market price relative to net profitsBelow historical industry averagePrice to BookShare Price / Book Value Per ShareCompares market capitalization to net asset valueRatio under 1.0 or industry normDebt to EquityTotal Liabilities / Shareholder EquityAssesses financial leverage and solvency riskLower ratios indicating strong solvencyFree Cash Flow YieldFree Cash Flow / Market CapEvaluates actual cash generation per shareHigher yields relative to treasury bondsAnalyzing the Price-to-Earnings RatioThe price-to-earnings ratio remains the most widely used metric in stock valuation. Comparing a firm's ratio against historical norms reveals whether shares trade at a discount. A low ratio often signals an opportunity, provided earnings remain stable.Assessing Price to Book and Free Cash FlowThe price-to-book ratio compares market capitalization directly against net assets. Meanwhile, free cash flow yield measures actual cash produced after capital expenditures. Robust cash generation ensures a business can fund operations, repay debt, and distribute dividends during economic downturns.Must Try: Value Investing 2025: How It Works for Smart InvestorsHow Investors Calculate Fair Stock Value?Understanding how investors calculate fair stock value requires estimating future earnings and discounting them to present terms.Discounted Cash Flow ModelingThe discounted cash flow method projects a company's cash flows five to ten years into the future. Analysts then apply a discount rate, often the weighted average cost of capital, to account for risk and the time value of money. Summing these discounted cash flows yields the intrinsic value per share.Relative Valuation ComparisonsRelative valuation compares a company's multiples against direct competitors. If a business boasts higher profit margins yet trades at lower valuation multiples than its peers, the stock presents a compelling value case.How to Know if a Stock is Undervalued or Overvalued?Learning how to know if a stock is undervalued or overvalued requires balancing raw quantitative metrics with qualitative business assessments.Compare current valuation multiples against five-year historical averages to spot temporary dips.Evaluate competitive advantages, such as strong brand equity, patents, or high customer switching costs.Check debt levels to ensure low valuation multiples are not caused by severe financial distress.Monitor insider buying activity to confirm corporate executives view their own stock as bargain-priced.How to Find Undervalued Stocks for Your Portfolio?Knowing how to find undervalued stocks requires systematic screening and regular research. Stock screeners allow investors to filter thousands of equities by price-to-earnings ratios, dividend yields, and debt levels. Combining quantitative filters with qualitative research helps narrow down a curated list of undervalued stocks worthy of deeper analysis.Investors must also remain vigilant against value traps. A stock that appears cheap based solely on low multiples may actually face permanent revenue contraction or technological obsolescence.ConclusionBuilding wealth through value investing relies on patience, emotional discipline, and rigorous financial analysis. Throughout this article, we explored how to evaluate core financial statements, leverage valuation metrics like price-to-earnings and price-to-book ratios, and apply discounted cash flow models to determine intrinsic worth. We also covered practical ways to screen for potential candidates while protecting your capital against value traps caused by high debt or structural industry decline.Equipping yourself with real-time financial data and robust analytical tools turns market volatility into your greatest investment advantage. Finding exceptional companies at discounted prices creates a durable margin of safety for your financial future.To track market trends, run custom equity screeners, and access live valuation charts, explore our comprehensive research suite today to make confident, data-driven investment decisions.FAQsWhat is the difference between value investing and growth investing?Value investing focuses on buying established companies that trade below their intrinsic value, offering low valuation multiples and a high margin of safety. Growth investing targets companies expected to expand revenues and earnings at above-average rates, where investors accept higher valuation multiples in exchange for strong future capital appreciation potential.How do high interest rates impact stock valuation models?Higher interest rates increase the discount rate used in valuation models like discounted cash flow analysis. As the discount rate rises, the present value of future projected cash flows decreases. This reduction lowers calculated intrinsic values across the market, particularly impacting growth stocks with cash flows weighted far into the future.What role does a margin of safety play in value investing?A margin of safety represents the difference between a stock's calculated intrinsic value and its current market price. Buying shares significantly below their fair value provides a protective cushion against analytical errors, unexpected economic downturns, or temporary operational setbacks, ensuring long-term capital preservation for disciplined value investors.Why do market panics create opportunities for value investors?Market panics trigger widespread emotional selling where investors liquidate positions regardless of underlying business quality. This systemic fear drives share prices of financially sound companies far below their intrinsic value. Disciplined value investors capitalize on these temporary dislocations to acquire high-quality assets at deep discounts.How frequently should investors rebalance their value portfolios?Investors should review their value portfolios semi-annually or annually to reassess intrinsic value calculations. Rebalancing involves trimming positions that have reached or exceeded their fair market value and reallocating capital into newly discovered undervalued opportunities, ensuring optimal portfolio performance and continuous risk management.

What is IPO Investing, and How Does it Work for You?
Articles

What is IPO Investing, and How Does it Work for You?

Quick TakeawaysNavigating IPO investing allows retail market participants to access newly public companies during early growth phases.Financial data from Renaissance Capital reveals that global IPO activity raises hundreds of billions in capital across major exchanges annually.Evaluating an S-1 prospectus filing helps investors analyze revenue metrics, executive compensation, debt loads, and growth drivers.Understanding lock-up expiration periods prevents unexpected portfolio losses when insiders sell initial holdings post-launch.Diversifying early public stock allocations protects long-term wealth against initial trading volatility and market sentiment shifts.Watching a dynamic young company make its stock market debut creates immense excitement for retail investors seeking high-growth opportunities. Getting started with IPO investing allows everyday market participants to purchase shares of private companies as they transition into publicly traded corporations. According to market intelligence data from Renaissance Capital, initial public offerings raise over $100 billion in capital globally each year, giving investors early access to industry innovators.However, jumping into public debuts without analyzing company fundamentals exposes your capital to significant market volatility. While successful public offerings generate huge wealth, hype-driven buying often leads to steep early trading losses. In this complete beginner guide inspired by CIBC Investor's Edge, we will explore core IPO mechanics, detail step-by-step participation processes, analyze key investment risks, review prospectus evaluation strategies, and answer your top investing questions.What is IPO Investing?IPO investing refers to purchasing shares of a company when it undergoes an Initial Public Offering (IPO), transitioning from a privately held entity into a publicly traded corporation. During this milestone event, the company issues new or existing equity shares to the public on a major stock exchange for the very first time.For investors, participating in an IPO offers a ground-floor opportunity to own equity in expanding businesses before they mature. However, because newly listed companies lack long-term public trading histories, buying IPO shares requires careful analysis of corporate prospectuses, valuation metrics, and broader market sentiment.All the Key Factors in Evaluating IPO Investment RisksUnderstanding IPO investment risks protects your capital against speculative price bubbles and unexpected market downturns:Limited Historical Financial Track Record: Unlike established public companies with decades of audited filings, newly public firms offer limited public track records. Investors must rely primarily on S-1 registration statements to evaluate long-term profitability pathways.Lock-Up Expiration Selling Pressure: Company insiders, founders, and early venture capitalists are subject to lock-up agreements preventing share sales for 90 to 180 days. When these lock-up periods expire, sudden increases in market share supply can depress stock prices.Initial Price Volatility and Hype: Opening trading days are often driven by sentiment, speculation, and media coverage rather than underlying financial fundamentals, leading to sharp price fluctuations.Uncertain Valuation Standards: Underwriting banks set initial offering prices based on institutional demand, which can sometimes overvalue a company relative to its actual earnings potential or industry peers.Risk of Capital Misallocation: Funds raised during an IPO may be used primarily to pay down old company debt or cash out early venture capital investors rather than driving future research, development, and market expansion.Must Try: Stock Market Trends 2026: Smart Strategies For InvestorsHow to Start Investing in IPOs for Beginners?Learning how to start investing in IPOs for beginners requires understanding how initial shares are priced and allocated before trading begins:Open an Eligible Brokerage Account: Verify that your broker provides retail access to conditional IPO offerings and meets baseline portfolio account minimums.Review the Preliminary Prospectus (S-1 Filing): Study the company's financial history, executive management team, operational risks, and growth strategy carefully.Submit an Indication of Interest (IOI): Place a conditional purchase request detailing the number of shares you wish to buy at the target price range.Confirm the Final Share Allocation: Review your confirmed share allotment on the pricing night before public trading opens on the exchange.Monitor Initial Secondary Market Trading: Track stock price action, trading volume, and market sentiment as shares begin trading publicly.Following this structured process ensures you navigate how to invest in IPOs safely and systematically.Pros and Cons of Investing in IPOsEvaluating the pros and cons of investing in IPOs helps balanced investors weigh potential gains against early market risks:Investment AdvantageMarket Risk FactorEarly Stage Growth PotentialLimited public financial operating historyGround-Floor Pricing OpportunitiesHigh initial price volatility during opening weeksPortfolio Sector DiversificationPotential insider lock-up period selling pressureInstitutional Backing ConfidenceHype-driven overvaluation risks at launchHow to Evaluate a Company's IPO Before Investing?Knowing how to evaluate a company's IPO before investing ensures you separate quality businesses from temporary market hypes:Examine Revenue Growth Trends: Verify consistent top-line revenue expansion over consecutive fiscal quarters rather than single-year spikes.Assess the Competitive Moat: Identify proprietary technology, strong brand equity, or network effects that defend market share.Analyze the Use of Proceeds: Check whether raised capital pays off heavy existing debt or funds productive research and development expansion.Inspect Leadership and Insider Retention: Ensure key executives retain meaningful equity stakes to align their interests with long-term shareholders.Mastering what to check before investing in an IPO helps you spot enduring market leaders early.How to Decide if an IPO is Worth Investing in Today?Learning how to decide if an IPO is worth investing in requires assessing current market conditions alongside individual company valuation metrics.During bullish economic cycles, market sentiment often inflates valuation multiples far beyond reasonable fundamental levels. Comparing a debut company's price-to-sales or price-to-earnings ratios against established industry peers reveals whether the stock carries a fair valuation.Investors interested in investing in IPO stocks can also consider waiting until after the first quarterly earnings report. Observing how management delivers on guidance in the public eye provides valuable clarity before committing capital.How to Invest in an IPO Before It Goes Public?Understanding how to invest in an IPO before it goes public involves acquiring pre-IPO shares or participating through primary brokerage allocations.Primary share allocations are distributed through lead underwriting investment banks to institutional clients and eligible retail brokerage partners. Retail investors who meet specific account balance requirements can submit indications of interest directly through participating trading platforms before the final offer price is set. Mastering IPO investing for beginners builds a foundation for long-term wealth creation.Essential Reads: How Stock Investment Strategies Help in Making Better Moves?ConclusionNavigating IPO investing offers an exciting gateway to participate in corporate growth stories right as companies enter public equity markets. Throughout this comprehensive investment guide, we defined core IPO concepts, detailed key investment risk factors, outlined step-by-step participation workflows, weighed strategic pros and cons, and detailed prospectus evaluation techniques. While public debuts offer early growth exposure, maintaining disciplined risk controls protects your capital from hype-driven volatility. Taking time to analyze balance sheets, evaluate competitive moats, and track lock-up expiration dates ensures your investment decisions remain grounded in sound fundamental analysis. Realizing long-term financial independence requires building a diversified portfolio anchored by thoroughly researched, high-quality companies.Are you ready to track real-time stock quotes, analyze market trends, and make informed equity investments with total confidence? Connect with market analytics tools today to elevate your trading strategy!FAQsWhat is the minimum investment required to buy IPO shares?The minimum investment required to participate in an IPO depends entirely on your brokerage platform's specific rules. While traditional underwriting banks often require high account balances, modern online brokers allow retail clients to request allocations starting at just a few hundred dollars per offering.How does the underwriting process work for public offerings?Investment banks serve as underwriters to facilitate the public transition. Underwriters evaluate company financials, handle regulatory SEC filings, conduct global investor roadshows, establish initial price ranges based on institutional demand, and stabilize early trading prices once public market transactions commence.What is an S-1 registration statement in stock investing?An S-1 registration statement is a mandatory SEC filing required for US companies entering public markets. It provides comprehensive financial data, operational risk factors, corporate ownership structures, executive compensation, and explicit details regarding how the company intends to utilize funds raised from the offering.Why do some IPO stocks fall below their offer price on opening day?IPO stock prices decline below their offer price when initial public demand falls short of underwriter expectations. Overambitious initial pricing, broader stock market downturns, negative industry news, or weak institutional order books can cause immediate selling pressure when public trading begins on exchange floors.What is the difference between a direct listing and a traditional IPO?In a traditional IPO, new shares are created, underwritten by investment banks, and sold to raise fresh capital. In a direct listing, existing shareholders and insiders sell current shares directly to the public on the stock exchange without intermediate underwriters or new capital creation.

What is Portfolio Rebalancing and How Does it Work for You?
Articles

What is Portfolio Rebalancing and How Does it Work for You?

Key TakeawaysPortfolio Rebalancing nudges your investments back to their planned mix once the market has pushed some assets out of line.Its real job is managing risk, so your portfolio still fits how much volatility you can live with.You can rebalance by the calendar, by thresholds, or by mixing both, so choose whichever you'll actually stick with.Most people only need a check once or twice a year, or when something drifts about five points.Taxes and fees can eat into gains, so lean on new contributions and retirement accounts before you sell anything.Picture a tidy 60/40 mix of stocks and bonds that you set up years ago and then ignored. When you finally log in, stocks have run so hard that they're nearly three-quarters of the total. Nothing looks wrong on the surface, yet you're carrying far more risk than you ever agreed to take on. Portfolio Rebalancing is the simple habit that fixes this problem, and here's how it works in plain English.What is Portfolio Rebalancing?Portfolio Rebalancing means selling a bit of what has grown and buying what has lagged so you match your plan. It isn't about predicting the market or squeezing out extra return, since the real target is steady, manageable risk. Think of it as steering a car back into its lane after a sudden gust of wind.A Simple ExampleSay you hold 60% stocks and 40% bonds, and a great year pushes stocks up to 70% of the total. You haven't changed a single thing, yet your risk has quietly crept higher while the market did its work. Sell enough stocks to buy bonds, and you're back at 60/40 with the risk you originally wanted.What are the Portfolio Rebalancing Benefits?The biggest Portfolio Rebalancing Benefits are control and calm, and both matter more than most beginners expect at first. You decide how much risk you can carry, and rebalancing keeps you there even when one asset takes off. It also gives you a clear rule to follow, which matters most when the headlines get scary and loud.Risk stays where you set it, so a single winning asset can't quietly take over your whole portfolio.You sell high and buy low almost by accident, because you trim what's up and top up what's down.Rules beat nerves, since a written plan keeps you from panic selling or chasing whatever's trending this week.Your mix keeps pace with your life, which is handy when jobs, families, and retirement dates shift over the years.How Does the Portfolio Rebalancing Process Work?The Portfolio Rebalancing Process sounds technical at first, but it really boils down to four plain and simple steps. You start with a written target, check where you stand, work out what needs to move, then place trades. Do it on a regular schedule, and it becomes a quick routine rather than a big, time-consuming project.1. Set Your Target AllocationFirst, decide what share of your money belongs in stocks, bonds, cash, and anything else you own. Your age, your goals, and your honest tolerance for market ups and downs should drive those numbers every time. If you're unsure where to begin, this guide to setting financial goals before investing is a helpful starting point.2. Measure Your Current WeightsNext, add up what each asset class is worth across every account you have, including your workplace plan. Divide each total by your full portfolio value, and you'll see today's percentages for every asset class you hold. Compare those numbers with your targets, and the size of the drift jumps out at you right away.3. Decide What to Buy or SellNow look at each gap, both in percentage points and in plain dollars, so the trade sizes feel real. Anything overweight needs a trim, while anything underweight needs fresh money to bring the whole portfolio back toward its target. Whenever you can, send new deposits to the underweight pieces first, because that avoids selling and keeps costs low.4. Place Trades and Record ResultsMake your trades in tax-friendly accounts first, since sales inside a retirement account rarely cause an immediate tax bill. Afterward, jot down the date, your new weights, and any fees you paid, even if it's just a quick note. That little log saves you from guessing next time and makes the whole routine much easier to repeat.Which Portfolio Rebalancing Methods Work Best?There are a few Portfolio Rebalancing Methods to choose from, and none of them is the single right answer. Each one trades a little bit of effort, cost, or precision for something else that matters to you more. Honestly, the best method is the one you'll still be following three years from now, even on a busy week.MethodHow It WorksBest ForCalendarRebalance on a fixed date, such as every JanuaryBusy investors who want a simple routineThresholdRebalance when an asset drifts past a set bandInvestors who prefer reacting to real market movesHybridCheck on a schedule, but trade only if bands are breachedInvestors who want discipline and lower trading costsCalendar-Based RebalancingWith this method, you pick a date, check your weights, and trade only if something has moved away from target. It's easy to remember, and many brokers can automate it for you so you never have to think about it. The downside is that it sometimes triggers trades when your portfolio has barely budged, which means paying extra fees.Threshold-Based RebalancingHere you set a tolerance band, such as five percentage points above or below each target weight in your plan. You only trade when an asset crosses that line, so calm stretches in the market don't cost you anything. The catch is that you need to keep an eye on your accounts, or set up alerts with your broker.What are the Best Portfolio Rebalancing Strategies?Good Portfolio Rebalancing Strategies go a step further than simply selling your winners and buying the laggards. They also look at taxes, trading costs, and how much time you really have to spend on your money. Start with the easiest idea below, then add another one once you feel comfortable and know how it works.Use New Contributions FirstIf you add money to your accounts every month, point that fresh cash at whatever is currently underweight. You rebalance this way gently, and you skip both the trading fees and the capital gains taxes that selling brings. For many people with steady paychecks, this one simple habit does most of the heavy lifting all by itself.Rebalance Inside Tax-Advantaged AccountsTrades inside retirement accounts usually don't trigger an immediate capital gains bill, so do your bigger adjustments there. Tax rules vary by country and account type, so check yours before you move a large amount of money. It's also worth reading about how index rebalancing affects investors, since some funds shift holdings on their own.What are the Easiest portfolio rebalancing techniques to Start With?If all of this feels like a lot, a few portfolio rebalancing techniques take almost no effort. You can pick one of them, try it for a full year, and layer on another one later. None of them needs any market expertise, and each one cuts drift without stealing your evenings or your weekends.Automatic rebalancing is a setting many brokers and funds offer, and it restores your mix on a schedule.Target-date and balanced funds handle everything inside the fund, so you can hold one and skip the manual work.Dividend redirection sends your payouts to whichever asset is currently underweight, nudging you back toward target for free.Partial rebalancing moves you only halfway back, which trims taxes and fees while still cutting most of the extra risk.What are the Key Portfolio Rebalancing Rules?Your Portfolio Rebalancing Rules don't need to be fancy, but they do need to be written down. A short list keeps you steady when the market gets loud, and every single headline sounds urgent and important. Stick to it, because small, boring adjustments tend to beat big, dramatic moves over the long haul.Set a target allocation for every account you own, and make sure they all follow one overall plan.Choose a tolerance band, often five percentage points per asset class, and act only when it's crossed.Review on a fixed schedule, even when markets feel calm, and your account balance looks perfectly healthy to you.Use new cash and tax-advantaged accounts first, before you sell anything at all in a regular taxable account.Don't ditch the plan because of scary headlines, short-term fear, or overconfident predictions from total strangers on the internet.How Often Should You Rebalance Your Portfolio?For most investors, once or twice a year is plenty, and many are fine with just once. Checking more often usually adds trading costs and tax bills without improving your results by very much at all. Your own sweet spot depends on how volatile your holdings are, how large your accounts are, and your tax situation.Time-Based Versus Drift-Based ReviewsA yearly review suits calm, long-term investors with simple portfolios who like a predictable routine they can plan around. A drift trigger suits people who want to react sooner when one asset class lurches away from target. Many investors combine the two, getting a regular checkup plus protection against sudden swings that happen between scheduled reviews.Signs it is Time to ActDon't wait for your next review if one asset breaks its band, your goals change, or a life event lands. Retiring, switching jobs, or receiving an inheritance can all justify an immediate look at your whole target allocation. Treat these moments as real checkpoints, and update your written plan before you place any new trades or transfers.ConclusionPortfolio Rebalancing isn't glamorous, but it quietly keeps your risk in line with your goals as markets rise and fall. Pick a method, write down a few simple rules, and check in on a schedule that fits your life. Lean on new contributions and tax-friendly accounts first so your costs stay low, and tie every trade to your plan. This article is general education only, so please talk with a licensed financial advisor before making investment decisions.Frequently Asked QuestionsIs Portfolio Rebalancing worth it for small investors?Yes, because even small portfolios drift over time and end up riskier than their owners ever planned for. New contributions, automatic rebalancing, or a balanced fund can keep the cost close to zero for you.Does Portfolio Rebalancing trigger taxes?It can, because selling profitable holdings in a taxable account may create capital gains taxes on your returns. Rebalancing inside retirement accounts usually avoids this, and new deposits can fix drift without making taxable sales.What is a good rebalancing threshold?Many investors use a five percentage point band around each target, though plenty choose something a little different. Tighter bands mean more trades and costs, while wider bands let drift grow before you finally act.Can I rebalance without selling investments?Yes, you can send new contributions and dividends to the underweight asset class until the mix returns. It avoids trading costs and taxes, although it works best when you keep adding money fairly often.Should I rebalance during a market crash?Often yes, if your plan says so, because rebalancing means buying cheaper assets with money from the winners. Follow your written rules, and don't let panic push you into selling everything near the very bottom.

Roth IRA or 401k: Which Account is Best for You in 2026?
Articles

Roth IRA or 401k: Which Account is Best for You in 2026?

Quick TakeawayChoosing between a Roth IRA or 401k depends on your current tax bracket, future income expectations, and access to employer matching.A traditional 401(k) provides upfront tax deductions on contributions, while a Roth IRA offers tax-free growth and tax-free withdrawals in retirement.Employer 401(k) matching dollars represent an instant 100 percent return, making it the top priority for initial retirement contributions.Annual contribution limits favor 401(k) accounts, allowing up to $24,500 compared to $7,500 for Roth IRAs for taxpayers under age 50.Combining both accounts creates tax diversification, allowing retirees to manage income brackets and minimize tax burdens effectively.Deciding where to invest your hard-earned income for retirement can feel like navigating a complex financial maze. When deciding whether to fund a Roth IRA or 401k first, everyday investors face a pivotal choice that shapes their long-term tax liability and total accumulated wealth. According to retirement data from Fidelity Investments, workplace retirement plan balances continue to reach record highs, yet millions of workers miss out on tax optimization by failing to pair employer plans with individual accounts.Balancing immediate monthly budgets with long-term retirement goals requires understanding how distinct account structures treat your contributions and future withdrawals. Making the wrong choice can mean handing over thousands of unnecessary tax dollars to the government during your golden years. In this comprehensive financial guide, we will break down account definitions, analyze core tax differences, evaluate contribution limits, and outline a step-by-step strategy to maximize your retirement returns.What is a 401k?A 401(k) is an employer-sponsored retirement savings plan that allows eligible workers to contribute a portion of their paycheck toward long-term investments. In a traditional 401(k), contributions are made with pre-tax dollars, which lowers your taxable income in the year you make the contribution.Your money grows tax-deferred inside the account until you begin taking withdrawals during retirement. At that point, distributions are taxed as ordinary income. Many employers offer a matching contribution, effectively providing free money up to a specific percentage of your salary. Additionally, some companies now offer a Roth 401(k) option, which combines workplace contribution limits with post-tax treatment.What is a Roth IRA?A Roth IRA is an individual retirement account that you set up independently through a brokerage firm, completely separate from your employer. Contributions to a Roth IRA are made using after-tax dollars, meaning you do not receive an immediate tax deduction in the year you deposit the funds.However, the primary power of a Roth IRA lies in its future tax treatment. Your investments grow completely tax-free, and qualified withdrawals after age 59½ are entirely exempt from federal and state income taxes. Because it is an individual account, a Roth IRA provides broad access to stocks, low-cost index funds, and ETFs, alongside the flexibility to withdraw original contributions anytime without penalty.Essential Reads: Traditional vs Roth 401k: Which Option Fits Your Taxes?Core Roth IRA vs 401(k) DifferencesUnderstanding the fundamental Roth IRA vs. 401(k) differences helps investors align their savings strategy with their current financial situation.Account FeatureTraditional 401(k) PlanRoth IRA AccountAccount ProviderEmployer-sponsored planIndependent brokerage accountTax TreatmentPre-tax contributions (tax-deferred growth)After-tax contributions (tax-free growth)Withdrawal TaxationTaxed as ordinary income in retirement100% tax-free qualified distributionsEmployer MatchAvailable in many corporate plansNot applicable (individual account)Investment SelectionCurated list of plan mutual fundsBroad market access to stocks, ETFs, & fundsEvaluating Roth IRA vs 401(k) TaxesComparing Roth IRA vs. 401(k) taxes reveals two distinct approaches to managing your lifetime tax burden.Current vs. Future Tax BracketsThe decision comes down to a simple question: Will your income tax rate be higher now or when you retire? If you are early in your career and currently in a lower tax bracket, paying taxes upfront through a Roth IRA is highly advantageous. Conversely, if you are in your peak earning years and face a high tax bracket today, the immediate pre-tax deduction offered by a traditional 401(k) provides welcome tax relief right away.Tax Diversification in RetirementHolding both account types provides valuable tax flexibility after you stop working. Having access to both pre-tax 401(k) funds and tax-free Roth IRA distributions allows you to control your reported taxable income year by year, keeping your total tax liability as low as possible during retirement.Examining Contribution Limits and Income RulesAnalyzing Roth IRA vs. 401(k) contribution limit guidelines highlights significant differences in how much money you can save annually.Annual Contribution LimitsA 401(k) allows for significantly higher annual savings capacity. Individual workers can contribute up to $24,500 annually into a 401(k), with additional catch-up contributions permitted for savers aged 50 and older. In contrast, the annual contribution limit for a Roth IRA is capped at $7,500 for savers under age 50.Income Eligibility ConstraintsAnyone with earned income can contribute to a 401(k) regardless of how much money they make. However, Roth IRAs enforce strict income eligibility limits set by the Internal Revenue Service. High earners whose modified adjusted gross income exceeds annual federal thresholds are restricted from contributing directly to a Roth IRA, though alternative strategies like a backdoor Roth IRA remain available.Weighing Roth IRA vs 401(k) Pros and ConsReviewing Roth IRA vs 401(k) pros and cons clarifies the practical benefits and limitations of each retirement vehicle.401(k) Advantages and DisadvantagesThe biggest advantage of a 401(k) is the employer matching contribution, followed by high annual limits and automatic payroll deductions. The primary drawbacks include limited investment choices, administrative account fees, and future income taxes owed on every dollar withdrawn during retirement.Roth IRA Advantages and DisadvantagesThe main benefit of a Roth IRA is tax-free income in retirement, unrestricted investment choices, and penalty-free access to original contributions if an emergency arises. The chief downsides are lower annual contribution caps and strict income eligibility requirements that exclude high-earning households.How to Allocate Your Savings Step by Step?Creating an optimal retirement savings order ensures you capture every financial benefit available:Secure Your Full Employer Match: Contribute enough money to your 401(k) to collect 100 percent of any company match. This provides an immediate, guaranteed return on your investment.Max Out Your Roth IRA: Once you secure your full 401(k) match, direct additional savings into a Roth IRA to lock in tax-free growth and expand your investment choices.Return to Your 401(k): If you hit the annual contribution limit on your Roth IRA and still have funds to invest, increase your 401(k) contributions toward the maximum allowable cap.Explore Supplemental Accounts: Consider contributing to a Health Savings Account (HSA) or taxable brokerage account for added flexibility and tax-advantaged healthcare savings.Must Try: Traditional IRA vs Roth IRA: What Helps in Building Wealth?ConclusionDetermining whether to fund a Roth IRA or 401k does not have to be an all-or-nothing decision. Throughout this guide, we defined both accounts, compared tax structures, evaluated contribution limits, and outlined an efficient funding strategy. A 401(k) provides immediate tax deductions, high contribution limits, and valuable employer matching dollars. Meanwhile, a Roth IRA offers complete tax-free growth, flexible investment choices, and penalty-free access to your principal contributions. By prioritizing your employer match first and then funding a Roth IRA, you create a powerful tax-diversified portfolio that maximizes your long-term wealth. Are you ready to optimize your retirement portfolio and secure your financial future with absolute clarity? Explore advanced market insights and financial planning tools today to build lasting wealth!FAQsWhat happens to my 401k when I change jobs?When leaving an employer, you can roll your 401(k) into your new employer's plan or transfer it into a rollover IRA without triggering taxes. Alternatively, you can leave the balance in your previous employer's plan if permitted or cash it out, though cashing out triggers income taxes and early withdrawal penalties.Can I contribute to both a Roth IRA and a 401k in the same year?Yes, you can contribute to both a Roth IRA and a 401(k) in the same calendar year, provided you meet the eligibility requirements for each account. Contributing to both accounts allows you to take advantage of employer matching dollars while building a source of tax-free retirement income.What is the 5-year rule for Roth IRA withdrawals?The 5-year rule requires that five tax years pass after your first contribution to any Roth IRA before you can withdraw investment earnings completely tax-free. This rule applies even if you are over age 59½, though original contributions can always be withdrawn at any time without tax or penalty.Are required minimum distributions mandatory for Roth accounts?Original owners of Roth IRAs are not subject to Required Minimum Distributions (RMDs) during their lifetime, allowing account balances to compound tax-free indefinitely. Under modern tax rules, Roth 401(k) workplace accounts are also exempt from RMDs, giving retirees total control over when they take distributions.How does an employer match work in a roth 401k plan?When you contribute to a Roth 401(k) using after-tax dollars, your employer can still match your contributions. Historically, employer matching funds were placed in a traditional pre-tax account, though modern regulations allow employees to elect tax-free employer match contributions if their workplace plan explicitly supports that option.

Ask stocky